

Business Operation · 2025
In this section23 topics
- Corporate Information4 items
- Dividend Policy2 items
- Major Shareholders3 items
- Business Strategies Overview6 items
- Material Changes & Developments1 item
- Use of Proceeds from Securities Offerings3 items
- Commitments Made in the Registration Statement1 item
- Group Operating-Structure Policy1 item
- Companies Where the Company Holds ≥10%1 item
- Shareholders with Potential Conflict of Interest1 item
- Relationships Among Major Shareholders2 items
- Shareholders' Agreement1 item
- Shareholding Diagram (Group Structure)2 items
- Income Structure4 items
- Product / Service Characteristics3 items
- Research & Development2 items
- Assets Used in the Business4 items
- Marketing Policy & Competition3 items
- Procurement of Products & Services2 items
- Product Information — Overview1 item
- Projects Under Construction1 item
- Debentures & Bills of Exchange3 items
- Convertible Securities1 item
Corporate Information
Company Name
MUANGTHAI CAPITAL PUBLIC COMPANY LIMITED
Telephone
0-2483-8888
Website
www.muangthaicap.com
www.muangthaicap.com
Dividend Policy
Dividend Policy
The Company adheres to a dividend payment policy, wherein dividends are not to exceed 50 percent of the net profit derived from the separate financial statements of both the Company and its subsidiaries each year, after accounting for corporate income tax deductions, legal reserve allocations, and any carried-forward accumulated losses. Dividends are distributed equally per share, as approved by the shareholders' meeting. However, the Board of Directors may pay interim dividends to shareholders whenever the Company is profitable enough. Following dividend disbursement, the shareholders' meeting will be informed and acknowledge the details in the subsequent meeting.
However, the dividend payment is subject to change depending on the business expansion plan, liquidity, the need for working capital to manage the business, and the Company’s business expansion including the economic conditions and other suitability in the future.
Historical Dividend Payments
| This Year | Last Year | 2 Years Ago | 3 Years Ago | 4 Years Ago | Metric | Description |
|---|---|---|---|---|---|---|
| 3.17 | 2.77 | 2.31 | 2.4 | 2.33 | Net profit per share (Baht : Share) | Net profit per share (baht : share) |
| 0.29 | 0.25 | 0.21 | 0.95 | 0.37 | Dividend per share (Baht : Share) | Dividend per share (baht : share) |
| 0 | 0 | 0 | 0 | 0 | Dividend stock ratio (Number of original shares: dividend shares) | Ratio of stock dividend payment (existing share : stock dividend) |
| 0 | 0 | 0 | 0 | 0 | Dividend share value per share (Baht : Share) | Value of stock dividend per share (baht : share) |
| 0.29 | 0.25 | 0.21 | 0.95 | 0.37 | Total dividend payment value (Baht : Share) | Total dividend payment (baht : share) |
| 9.15 | 9.02 | 9.09 | 39.58 | 15.88 | Dividend payout ratio to net profit (%) | Dividend payout ratio compared to net profit (%) |
Business Strategies Overview
Chairman's Message
The Company has remained firmly committed to conducting its business as a financial services provider in accordance with international standards. It upholds the principles of good Corporate Governance, transparency, and accountability to society and the environment, with the aim of achieving stable and sustainable long-term growth.
As the Chairman of the Board, I place great importance on my role in overseeing Corporate Governance and setting the Company’s strategic direction. This includes integrating sustainability principles (ESG) into decision-making processes and operations at all levels, from conducting business with integrity and managing risks prudently, to creating balanced and sustainable value for all stakeholders.
Concurrently, Muangthai Capital Public Company Limited has accelerated its digital transformation by embedding technology and data capabilities into its core operations. This initiative has strengthened the Company's ability to operate more efficiently, deliver higher-quality services, and manage risk more effectively, ensuring customers receive responses that are both swift and secure.
The Company has prioritized international expansion by securing access to capital markets and forging partnerships with global allies to strengthen its financial foundation and sharpen its long-term competitive edge while remaining committed to drive business responsibly towards all stakeholders as well as upholding transparent, equitable, and accountable governance principles. The Board of Directors and Management have continued to collaborate closely, driving the Company forward on a path of stable, sustainable growth that generates meaningful and lasting value for shareholders and society.
(Adm. Apichart Pengsritong)
Chairman of the Board of Directors
Vision
We Will Be No. 1 Leader in The Microfinance Business.
MISSION
The Company must expand the service area to cover the whole country by opening both full branches and sub-branches, including service centers to cover all areas and regions of the country.
The Company must have the highest market share in each area where it has been launched for operation, and the customer base must increase every year.
Employees of the Company must conduct performance evaluations based on the highest loan amount per capita in the same industry.
The Company focuses on the supervision of internal management and use the 40 standard figures as a guideline for operations.
The Company provides customers with high-quality services and strives to achieve the highest customer satisfaction.
VALUE
Morality / Exertion / Perspective / Harmony / Discipline
Objectives
The Company focuses on growth by expanding the customer base through the expansion of branches to cover all areas in the country. The ultimate goal is to help improving financial inclusion of those unable to access funding from banks by being their alternative funding sources with fair and transparent financial costs. The company believes that distributing financial access to the people will help reduce financial inequality in the country which is the cornerstone of a sustainable economic system.
Goals
The Company is committed to delivering financial opportunities to Thai society in an inclusive and equitable manner, while driving the business toward its vision of becoming the number one leader in the Microfinance industry. With a clear strategic plan, the Company aims to expand internationally standardized services to cover all regions of the country, maximize customer satisfaction, serve as a key mechanism in elevating the nation's financial standards, and sustainably build a foundation of stability while improving the quality of life for Thai people nationwide.
Business Strategies
To be the No. 1 leader in microfinance, serving as a model on providing global standard financial services and expanding economic opportunities at all levels. The Company is committed to reducing disparities in access to financial services, while operating with integrity, transparency, and social responsibility to drive sustainable growth in the Thai economy.
Focusing on expanding branches to cover the entire country, aiming to provide access to high-quality financial services that meet global standards. This expansion will encompass all subdistricts and all 77 provinces of Thailand, ensuring equal access for all occupations and genders. The goal is to foster stable and sustainable career growth while enhancing long-term quality of life.
Maintaining the quality of the loan portfolio through efficient debt management, alongside prudent lending practices to control NPLs enhancing portfolio stability. Focused on reducing losses from repossessed asset (seized vehicles) while accelerating the disposal of assets acquired from customers into the market to reduce reserve provisions for bad debts and maintain a balance between the growth of the loan portfolio and the Company's long-term financial stability.
Developing innovations and products to meet diverse customer needs across both online and offline channels comprehensively, enhance the ability to retain the customer base, elevate financial service experiences to be efficient, convenient, rapid, and secure for users in the digital era, including, promoting the use of digital technology and data to enhance analytical capabilities and advantages for continuously developing new product of the Company in the future.
Regularly reviewing and improving policies and operational plans to maintain competitiveness in line with changes in the business environment, reduce risks that may impact the organization, and strengthen confidence among all stakeholders. This is achieved through a commitment to building business growth stability via efficient management processes and adherence to business ethics.
Other Information
| Name | Description | ||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
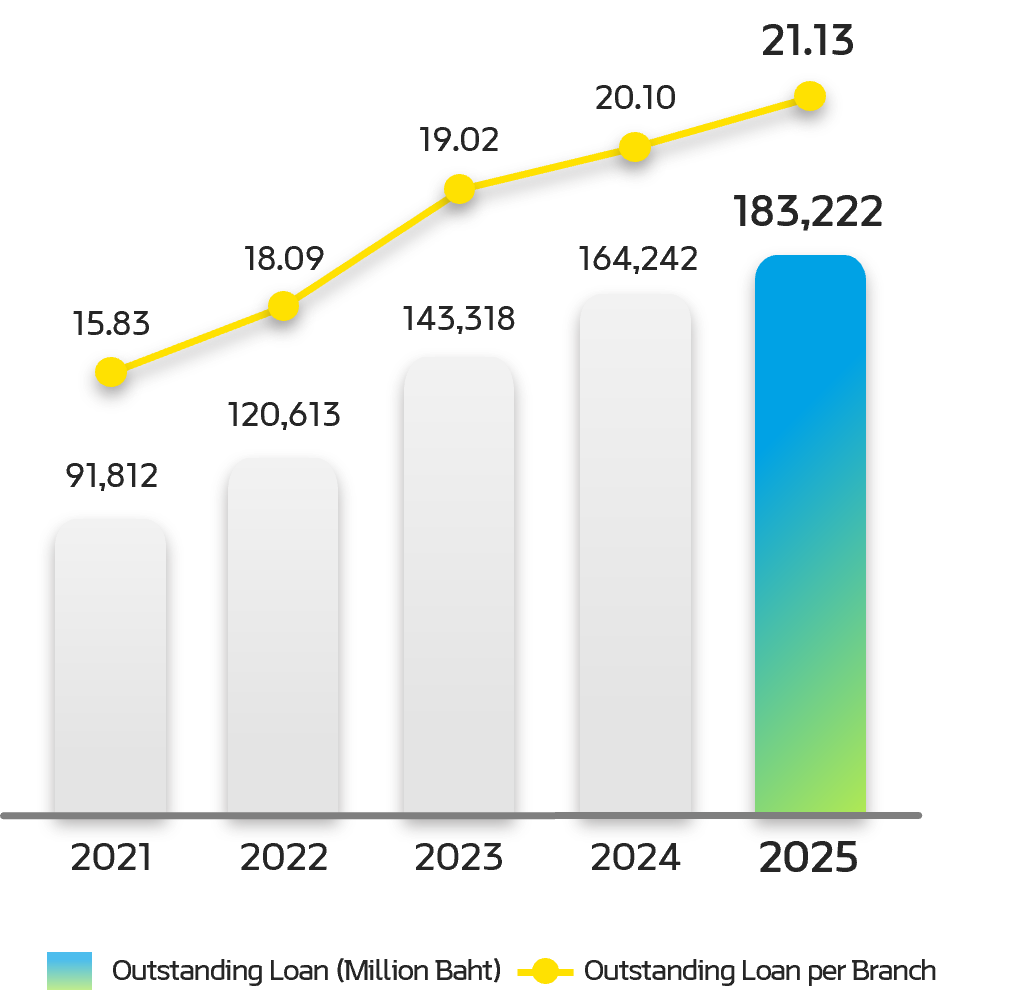
| Strategy 1 Expansion of Branch Network | The Company has continuously expanded its branches for over 33 years, with the primary goal of providing financial opportunities nationwide. It aims to serve all customer groups equally while maintaining international service standards to meet customer needs effectively. The Company prioritizes inclusive financial services accessible to everyone in society, playing a key role in improving the quality of life across the country. As of 2025, the Company has expanded its branch network to 8,673 branches across 77 provinces, from provincial to village levels. In the same year, 502 new branches were opened, reflecting the Company's commitment to expanding financial access nationwide. Additionally, the Company has increased funding sources for communities compared to the previous year, resulting in total outstanding loans of 21.13 million Baht, playing a crucial role in supporting businesses and livelihoods.
Outstanding Loan per Branch (Million Baht/Branch)
| ||||||||||||||||||||||||||||||
| Strategy 2 Excellent Service | The Company is committed excellent and high-quality services by cultivating a culture where employees provide friendly, prompt, attentive, and top-standard service, prioritizing customer needs. It also focuses on enhancing employee potential by developing skills that comprehensively and professionally meet customer demands. Moreover, the Company manages customer complaints efficiently, emphasizing timely, and precise problem resolution to foster long-term, positive relationships with customers. It maintains a continuous feedback and improvement system to delivering service excellence and elevate the customer experience. The Company enhances all aspects of its services to maximize customer satisfaction, building a strong and stable customer base that is a key driver for sustainable growth and long-term success, particularly in expanding the customer base and strengthening competitiveness in challenging markets. | ||||||||||||||||||||||||||||||
| Strategy 3 Portfolio Management | The Company places great importance on managing the loan portfolio to ensure high quality, reduce risks, and generate appropriate returns. This is achieved through continuous credit analysis and monitoring to manage the loan portfolio effectively. The Company also focuses on developing and improving technology to diversify products and create models tailored to all customer groups, aiming to ensure long-term stability of the loan portfolio. The following strategies are applied in the operation:
| ||||||||||||||||||||||||||||||
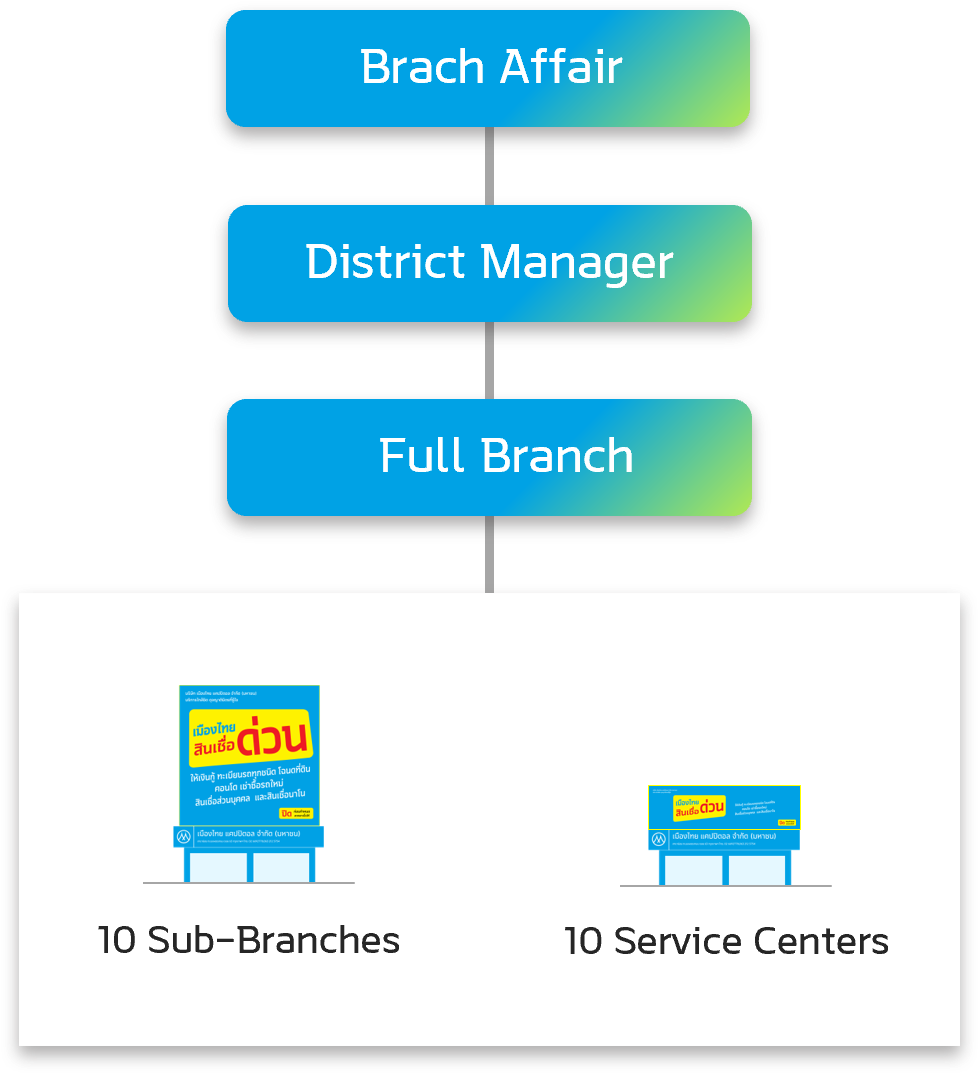
| Strategy 4 Management | Decentralization is the Company’s core management through a structure that delegates authority to full branches, sub-branches, and service centers across various regions. This strategy aims to foster strong growth, effectively maintain a retail customer base, support business expansion, and enhance customer service efficiency. The Company’s decentralized management includes the following guidelines:
|
Material Changes & Developments
Material Changes & Developments
| Year | Description |
|---|---|
| 2,023 |
|
| 2,024 |
|
| 2,025 |
|
Use of Proceeds from Securities Offerings
Is There Money Raised from a Securities Offering Still to Report On?
Yes
Offerings
| Type of Securities | Amount Raised Given As | Amount Raised (Million Baht) | Uses of the Money | Used as Declared? |
|---|---|---|---|---|
| Debt Instruments | 2873 | 35,689.53 | 2026-01 · Objective: Use the funds from the issuance of debentures and/or bills of exchange to repay the outstanding debt · Period type: 2871 · Start period: 2026-01 · Spent amount type: 2873 · Start spent amount: 24826.6 · Expected amount type: 2873 · Start expected amount range: 24826.6 · 2025-12 · Objective: For acquisition of assets, investments, or business expenses related to ongoing business operations and to expand the loan portfolio of the debenture issuance · Period type: 2871 · Start period: 2025-12 · Spent amount type: 2873 · Start spent amount: 10862.93 · Expected amount type: 2873 · Start expected amount range: 10862.93 | Y |
Law Governing the Debt Securities
Securities and Exchange Act B.E. 2535 (1992) as amended
Section 69 and 70 (Filing)
Section 82-89 (Information disclosure)
Personal Data Protection Act (PDPA) to collect, use and disclose information of shareholders, investors and parties related to the debt instruments
Regulations of the Stock Exchange of Thailand - Other applicable laws relating to debt instruments and financial contracts, including the Civil and Commercial Code (loan agreements and debt instrument contracts), applicable tax laws, and electronic transactions law
Notifications and rules issued by the Securities and Exchange Commission (SEC) regarding the issuance and offering of debt instruments, including the SEC Notification on applications for approval to offer debt instruments, the SEC Notification on disclosure requirements for securities issuers, and the relevant Debt Securities Regulations
Commitments Made in the Registration Statement
Are There Commitments or Conditions from an Offering or Listing?
No
Group Operating-Structure Policy
Description
Regarding the Company’s investments in the subsidiaries as of 31 December 2025, the Company holds investments in its subsidiaries, in which it owns 10 percent or more of the issued and paid-up shares, Muangthai Capital Public Company Limited directly holds 99.99 percent of the 3 subsidiaries.
The Company has no characteristics of cross-shareholding or indirect shareholding of the Company’s subsidiaries. Additionally, the Company has not provided or guaranteed a loan for other companies which are not the Company’s subsidiaries.
Companies Where the Company Holds ≥10%
Companies (≥10% Holding)
| Company Name | Address | Province | Zip Code | Telephone | Business Type | Security Type | Shares | Paid-up Shares |
|---|---|---|---|---|---|---|---|---|
| Muangthai Leasing Company Limited | Head office of Muangthai Capital Public Company Limited, No.332/1, Jaransanitwong Road | Bangkok | 10700 | 02-483-8888 | Hire-purchase | Common shares | 9,999,997 | 10,000,000 |
| Muangthai Leasing Insurance Broker Company Limited | Head office of Muangthai Capital Public Company Limited, No.332/1, Jaransanitwong Road | Bangkok | 10700 | 02-483-8888 | Insurance Brokerage | Common shares | 19,998 | 20,000 |
| Muangthai Pay Later Company Limited | Head office of Muangthai Capital Public Company Limited, No.332/1, Jaransanitwong Road | Bangkok | 10700 | 02-483-8888 | Installment loan | Common shares | 9,999,996 | 10,000,000 |
Income Structure
Introduction
The loan products of the Company are provided and accessed by more various groups of retail customers and entrepreneurs. The product designation, conditions, collaterals and credit line are appropriate for controlling default rate. In addition, the Company empathizes the monitoring process of debt tracking, planning on facing all risk factors that might occur, as well as including the NPL rate as one of the Key Performance Indicators (KPIs) to assess the performance of employees.
The Company’s revenue consists of vehicle title loan, land title deed loan, personal loan, nano finance loan. As the result of such operation, the revenue of the Company has been rising with the development of various products and services to meet the customers’ needs.
As the result of the Company’s operation in 2025, its primary revenue source was interest income, representing 97.63 percent of the total revenue.
Product / Service Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue from operations | Total revenue from operations | 30,739,249.21 | 100 | 27,902,281.19 | 100 | 24,526,176.33 | 100 |
| Interest income from loans receivables and hire purchase receivables | 30,009,816.45 | 97.63 | 26,956,210.88 | 96.6 | 23,500,467.97 | 95.82 | |
| Fees and service income | 572,167.3 | 1.86 | 780,710.9 | 2.79 | 920,922.22 | 3.75 | |
| Other | Other | 157,265.46 | 0.51 | 165,359.4 | 0.59 | 104,786.15 | 0.43 |
Export Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue | Total revenue from operations | 30,739,249.21 | 100 | 27,902,281.19 | 100 | 24,526,176.33 | 100 |
| Domestic | Domestic | 30,739,249.21 | 100 | 27,902,281.19 | 100 | 24,526,176.33 | 100 |
| International | International | 0 | 0 | 0 | 0 | 0 | 0 |
Other Income
| Operating Other Income | Non-Operating Other Income | Share of Profit |
|---|---|---|
| 1710 · As of year: 0.0 · Description: Total other income · As of yesteryear: 0.0 · As of year before yesteryear: 0.0 · 1711 · As of year: 0.0 · Description: Other income from operations · As of yesteryear: 0.0 · As of year before yesteryear: 0.0 | 1712 · As of year: 0.0 · Description: Other income not from operations · As of yesteryear: 0.0 · As of year before yesteryear: 0.0 | 1713 · As of year: 0.0 · Description: Share of profit · As of yesteryear: 0.0 · As of year before yesteryear: 0.0 |
Product / Service Characteristics
Introduction
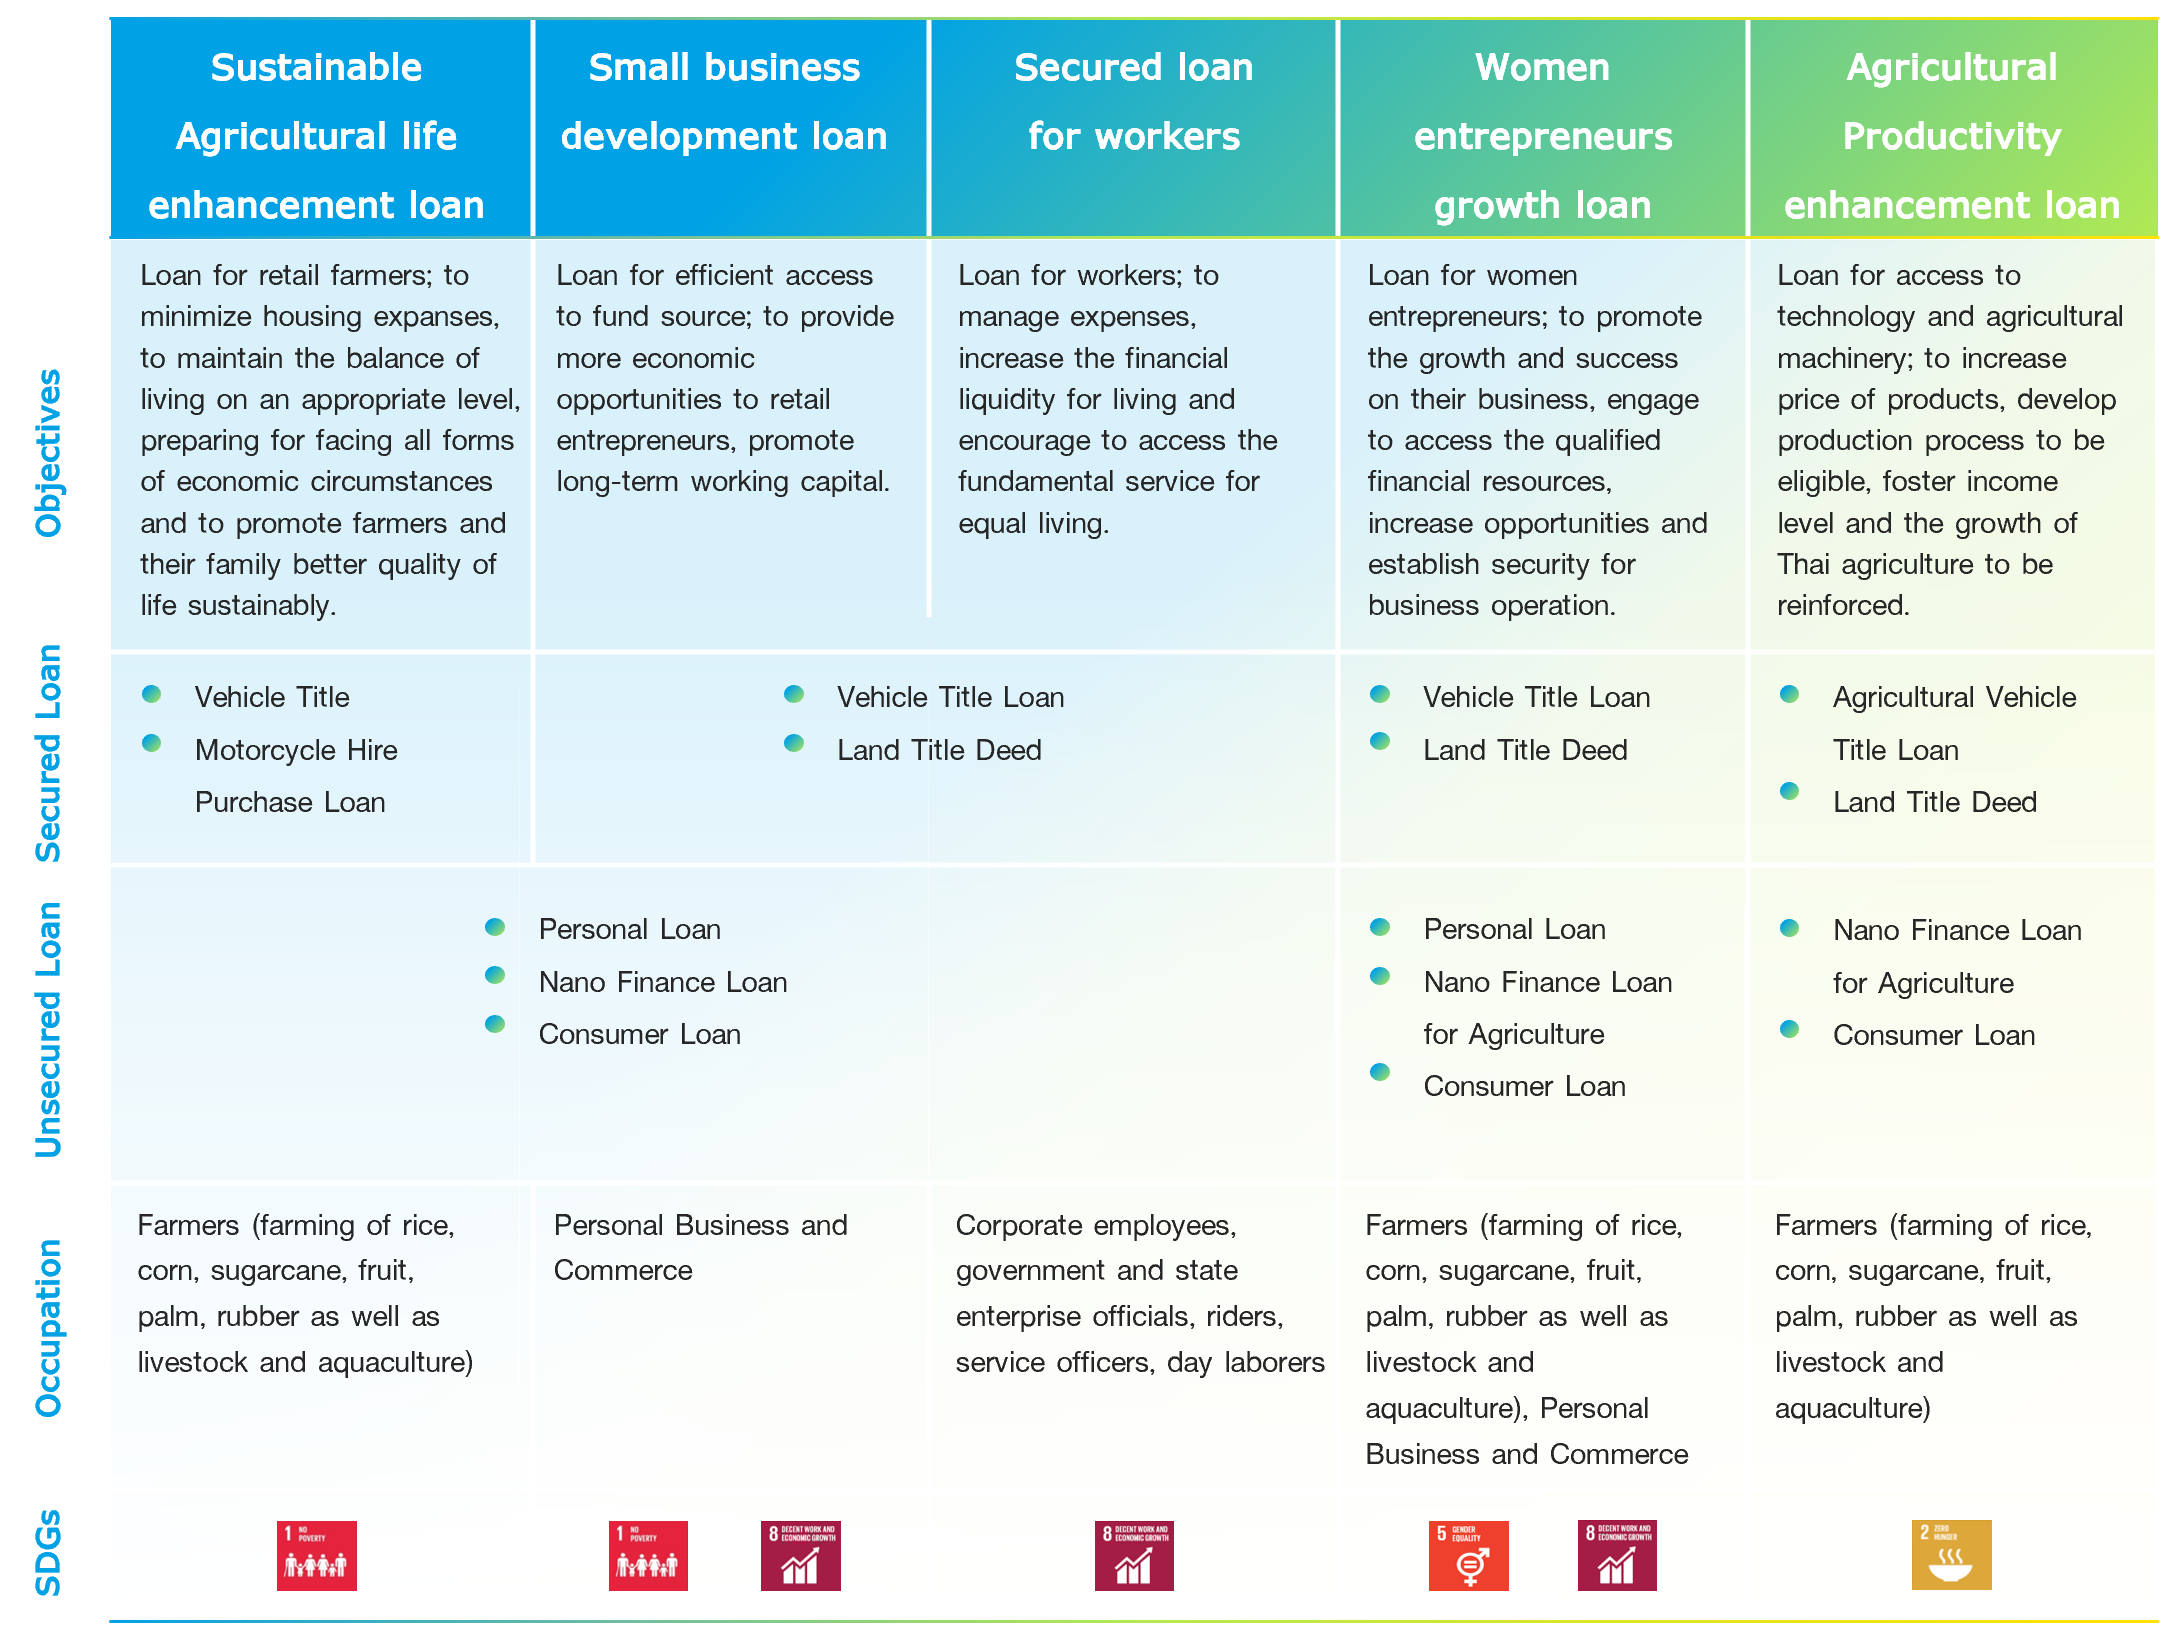
The Company has been committing to offering financial services to the group of retail customers more conveniently and to meet the variety of demands, covering the target group of customers such as farmers, corporate employees, government officials, state enterprise officials, freelancers and day laborers. It categorizes types of loan by analyzing these groups of customers, objectives of loan application, cost and risk management of each loan, ensuring that each loan is capable of providing an opportunity of financial liquidity, sustainable foundation establishment, long-term growth promotion and inclusively increasing quality of life. Furthermore, the Company has a loan approval method by focusing on responsible lending principles. This is conducted with the slogan “Excellent Service, Low Interest Rate” as well as a rapid loan approval and efficient service.
Business Type
3115
Business Groups
| Business Group | Description |
|---|---|
| Loan Services Business |
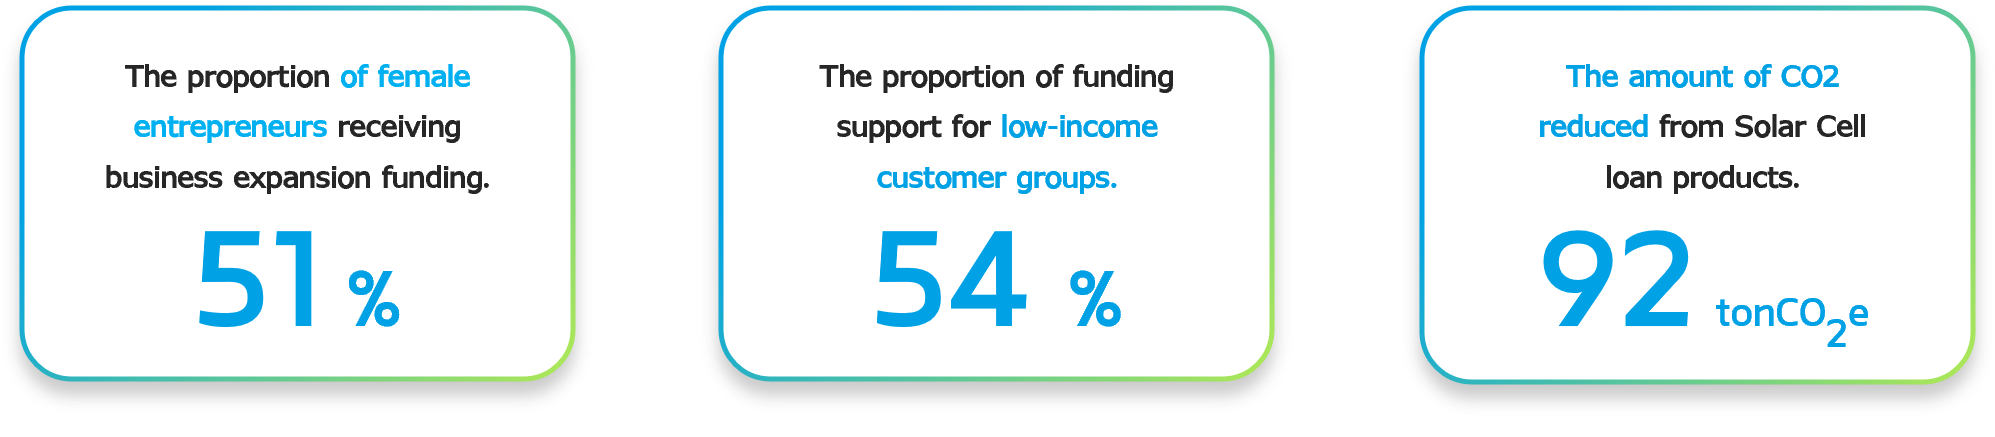
In 2025, the Company collaborated with the International Finance Corporation (IFC) to issue a Social Bond, aimed at expanding access to financial services for women entrepreneurs, promoting equality regardless of gender and occupation. This initiative reflects the Company's commitment to becoming a world-class organization that champions equal access to funding and sustainable credit service operations.
|
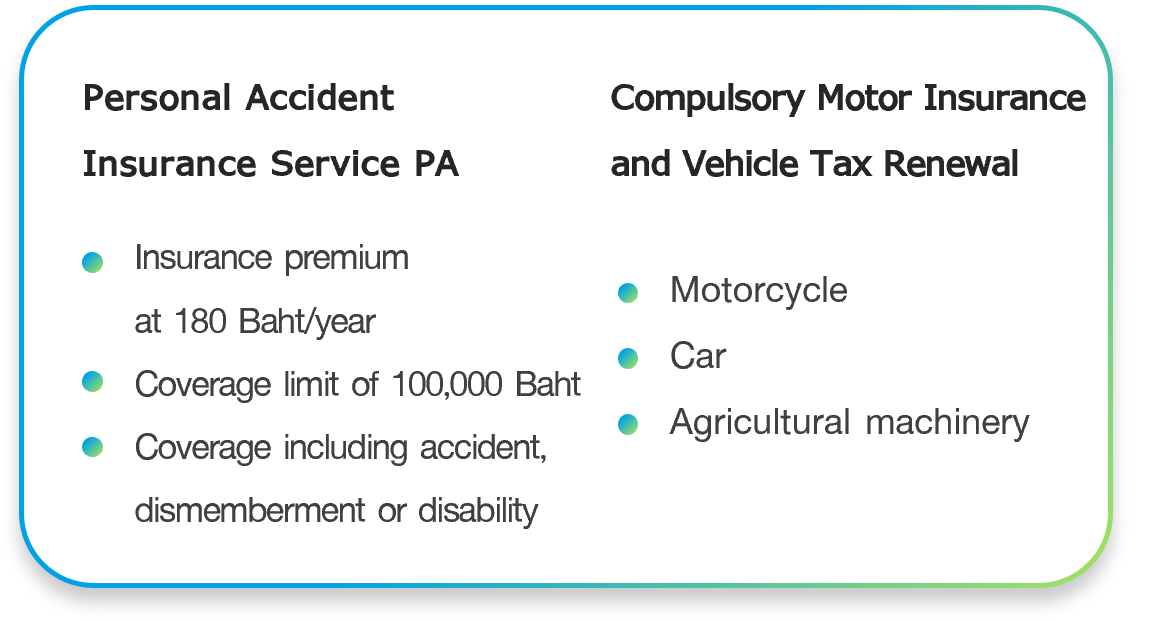
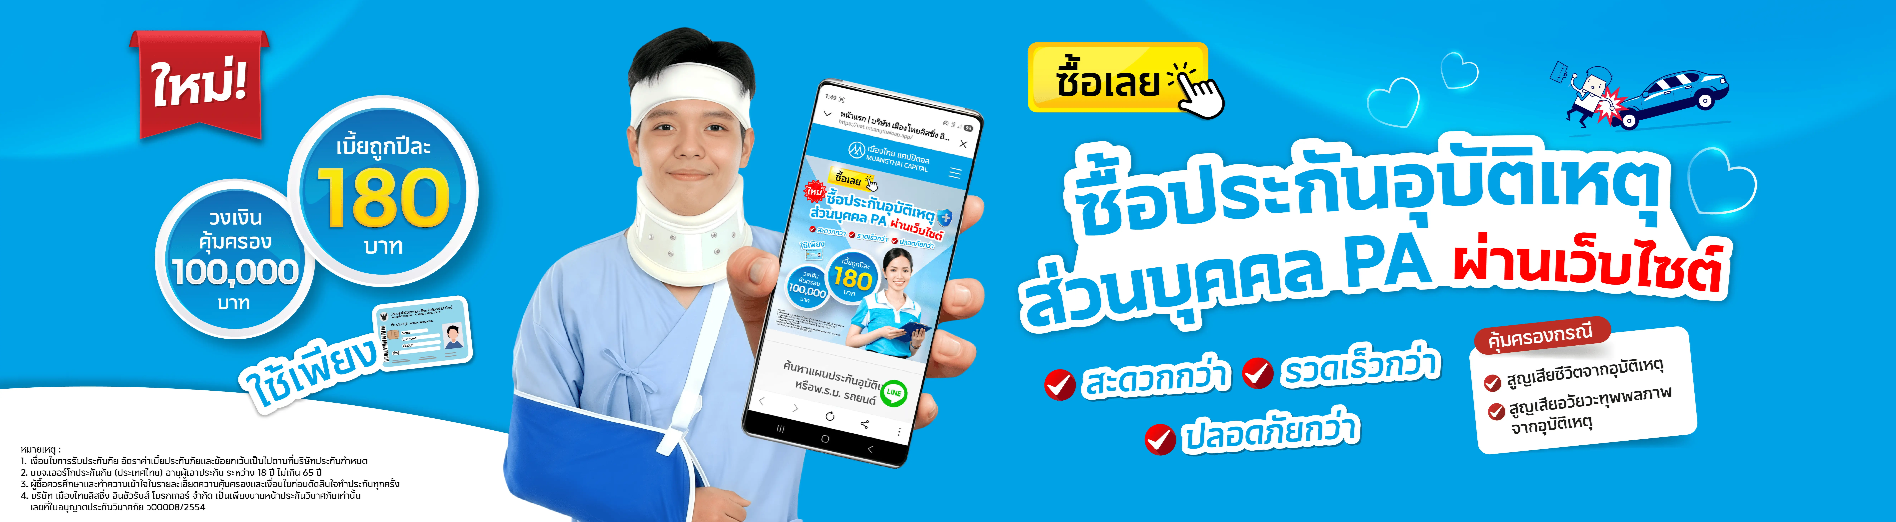
| Non–Life Insurance Broker Business | To provide personal accident (PA) insurance operated by non-life insurance broker of Muangthai Leasing Insurance Broker Co., Ltd.,offering coverage for accidental incidents. The service also includes compulsory motor insurance and vehicle tax renewal for facilitaiting customers. The services are provided at every branch nationwide.
|
Research & Development
Has R&D Policy (Y/N)
No
R&D Cost — Label
Research and development (R&D) expenses over the past 3 years (Million Baht)
Assets Used in the Business
Permanent Assets — Description
As of 31 December 2025, the Company had fixed assets that were used in business operations. The net book value is 1,221.82 million Baht with the head office building located at 332/1 Bangplad, Bangplad, Bangkok, Thailand. There are 12 buildings owned by the Company. Almost all of the Company’s branch offices are the rented buildings.
Permanent Assets — Appraisal
| Asset | Ownership | Obligation | Appraisal Value |
|---|---|---|---|
| Land | Owned by the Company | Without Obligations | 274.56 |
| Office buildings | Owned by the Company | Without Obligations | 351.61 |
| Building improvement | Owned by the Company | Without Obligations | 595.65 |
Intangible Assets — Description
As of 31 December 2025, the Company's intangible assets used in business operations had a total net book value of 62.73 million Baht, comprising software copyrights of various programs utilized by the Company, as disclosed in Note 8 to the Financial Statements.
Has Subsidiaries Investment Policy (Y/N)
No
Marketing Policy & Competition
Reporting Mode
3117
Marketing Policy (Overall)
Loan Product Development based on ESG with Asset-Based Assessment Approach
To provide a financial access to the retail customers and to clearly meet variety of demands, the Company categorizes type of loan by analyzing these groups of customers and objectives of loan application. This procedure is done to ensure that the financial access is capable of providing or raising the financial liquidity inclusively. Additionally, in 2025, the International Finance Corporation (IFC) invests in issuance of Social Bond, providing more opportunities of financial access for women entrepreneurs to embrace equality in gender and occupation.
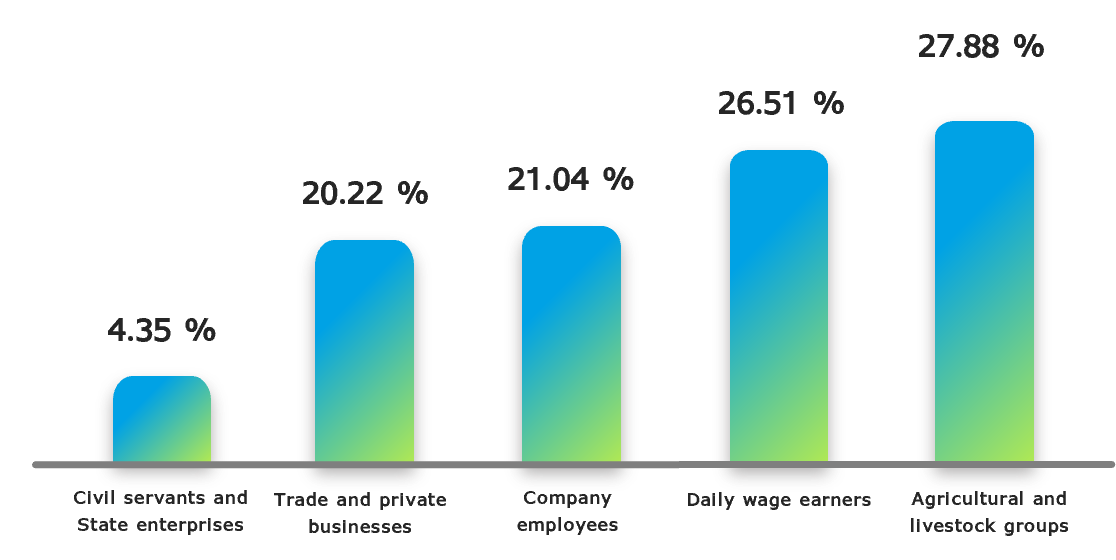
The proportion of customer occupation groups receiving Social Bond
Development of Ethical Standards in the Industry
The Company commits to encouraging financial awareness and discipline to cultivate borrowing responsibility among customers, assisting them to manage their own debt in the most beneficial way to their selves, family and society in overall. In a case that customer face difficulties of debt repayment, the Company has the appropriate remedial measure for them. The measure is stated clearly, transparently and easily to understand. This reflexes the commitment of the Company that is determined to establish a society where everyone can achieve a financial sustainability and to promote the development of domestic economic system growing sustainably in the long run.
Service Development of Security for Customer’s Occupational Health
The Company is committed to establishing the service standard, engaging employees on training and including a service assessment as one of the Key Performance Indicators (KPIs), based on customer service performance, as follows:
The Company has determined to provide excellent service to create a good impression experience for customers.
The Company has determined that all employees strictly adhere to the Company’s regulations and policies.
The Company ensures that office equipment is regularly inspected to ensure convenience and safety, avoiding any potential harm to customers.
The office is cleaned daily to maintain a clean workplace and a positive environment for both employees and customers.
The Company communicates with customers and other stakeholders via diverse platforms.
Complaints relating to employees and workplaces are managed, representing 100%
Development of Knowledge and Financial Discipline for Customers
Providing financial education through various channels Providing financial literacy and promoting financial management skills is crucial in helping the public plan their finances smoothly in daily life, reducing the risk of financial problems in the future. The focus is on reducing unnecessary debt and reliance on informal loans, which will help alleviate household debt in both short term and long term. The Company has implemented a policy of spreading knowledge through social media channels, with over 607,646 followers nationwide, on an ongoing basis.
Covering all aspects of financial management, including investment, savings, spending, and promoting debt management knowledge to establish a necessary foundation before incurring debt. This includes assessing repayment capacity, understanding types of loans, interest rate, and calculating both fixed and amortizing interest rate. Additionally, employees are encouraged to share essential information about loan applications, along with advice, precautions, benefits, and financial knowledge that directly benefits customers. This will help individuals manage their finances and debt more effectively.
Financial literacy articles for customers and the general public
Respecting Customer Satisfaction, Rights, and Personal Data
The Company places the highest importance on protecting the rights and interests of customers (Client Protection) in accordance with international standards, ensuring that every customer is treated fairly. This includes providing equal lending services, legal debt collection, the right to submit complaints, rejection of aggressive sales practices, transparent collateral management, financial assistance in times of difficulty, and the protection of personal data. The Company has communicated and disseminated the customer rights protection policy and the Personal Data Protection Act (PDPA) through its website and internal communication systems (MTCU). All employees have signed acknowledgment forms and completed training, followed by knowledge testing through the E-Learning system, to raise awareness and regularly review any legal changes.
Innovation Development and Digital Transformation
Muangthai 4.0 Application
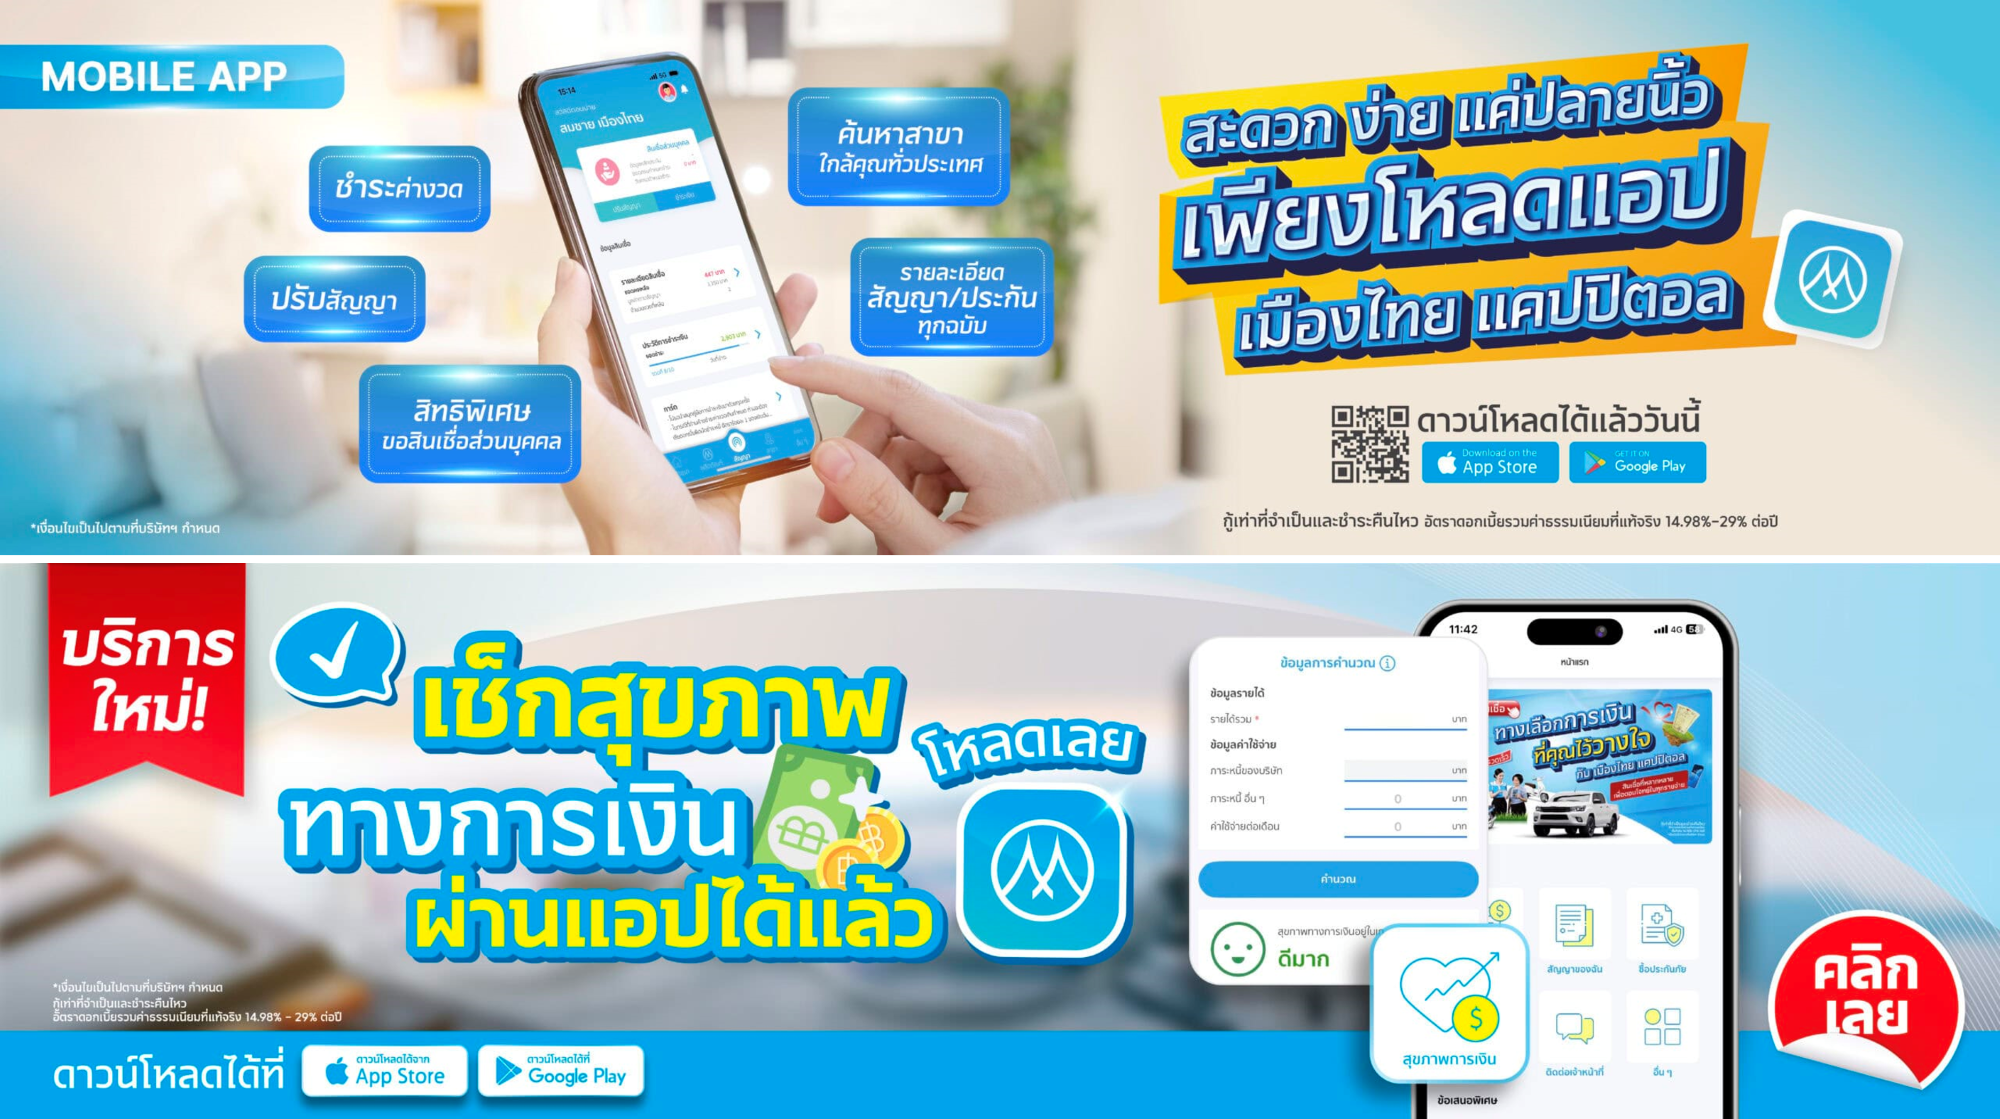
The Company has a policy to develop various online modules, such as online loan payments and other future services. By 2025, the Muangthai 4.0 app had 998,483 users, an increase of 26.71% compared to 2024. The Company continually reviews user feedback to improve app processes, ensuring greater convenience and speed of service. Additionally, the Company collaborates with commercial banks, foreign banks, and specialized financial institutions to expand bill payment channels and financial transactions through electronic channels. It has also adopted a new marketing strategy by enhancing special offers and new personal loans through the app for easier customer access.
AI Chatbot Development
Since 2019, the Company has developed an AI Chatbot to enhance and improve communication with customers through social media channels, making it more efficient and faster. The AI Chatbot can answer basic customer inquiries regarding loan products, the loan application process, and branch locations. The Company believes that the AI Chatbot is an important communication tool that can connect and support customer engagement, enabling the Company to maintain interactions with customers even outside of business hours.
Development of the Internal Sustainability System within the Organization
The Company is committed to elevating its standards to a global level through the systematic use of technology and innovation in performance management. This is achieved by developing a sustainability tracking and performance dashboard, covering economic, social, and environmental dimensions. The data-driven approach enhances efficiency in analysis, strategy adjustment, risk mitigation, and drives the organization toward sustainable growth in the following aspects:
Economic aspect
The Company has developed a credit management process at all levels, from service centers, sub-branches, and full branches to the overall organization, to ensure the quality of the loan portfolio, reduce risks, and generate appropriate returns. Key data, such as NPL ratio, product proportion, and number of branches, are used to analyze, monitor, and manage the loan portfolio through debt collection measures, debt restructuring, and risk assessment tools to prevent NPLs. This approach considers long-term impacts for the sustainability of both the organization and its employees.
Social aspect
The Company utilizes customer satisfaction evaluations, covering products, work processes, service locations, and feedback, as a key tool for continuous service analysis and improvement. Real-time monitoring of complaints is facilitated through a sustainability dashboard, enabling quick access to comprehensive data, effective issue tracking, and precise problem resolution. This approach strengthens customer relationships, enhances the Company's credibility, and delivers a positive customer experience.
Environmental aspect
The Company monitors the usage of key resources, including electricity, water, fuel, and paper, through Sustainability Dashboards that analyze and present data in an easy-to-understand format. These dashboards also assess greenhouse gas emissions and provide comparative data at the regional and branch levels, enabling informed decision-making and strategic adjustments that address issues effectively. This is coupled with raising awareness about resource usage, which not only contributes to climate change mitigation but also reduces costs and improves operational efficiency. In 2025, the Company successfully reduced electricity expenses by 38 million Baht and cut greenhouse gas emissions by over 4,128 tons of CO2 equivalent. This reflects the efficient use of resource data and reinforces the Company’s commitment to achieving tangible progress toward its Net Zero Emission target.
Industry & Competition (Overall)
Overview of Thai Economy and Impacts on the Industry
As of 31 December 2025, non-bank financial institution reported outstanding personal loans under supervision, excluding vehicle registration as collateral, totaling 14,894,210 million Baht. This is in comparison to the outstanding loans of the same type held by the Company, which amounted to 295,506 million Baht, representing 1.98% of the market share. The outstanding loans for personal loans under the supervision of title loans totaled 6,812,031 million Baht, compared to the Company’s outstanding loans of the same type, which amounted to 392,744 million Baht, representing 5.77% of market share. Nano finance had a total value of 5,157,867 million Baht, compared to the outstanding loans of the same type held by the Company, which amounted to 92,935 million Baht, representing 1.80% of the market share.
Currently, the Thai economy has faced challenges from various factors, including inflation affecting the cost of living, the global economic slowdown, and tighter monetary policies. The high policy interest rates have increased financial costs, impacting household spending and business investment. Although the tourism sector has been recovering steadily and serves as a key driver of the economy, the export sector and domestic consumption continue to grow at a limited pace. As a result, there has been an increased demand for credit from nonbank financial institutions, as commercial banks have tightened their lending policies. This has led individuals and businesses who are unable to access bank loans to turn to non-bank credit services more frequently.
Competition Overview of the Industry in the Previous Year
In 2025, the microfinance or small-scale lending sector in Thailand faced economic volatility and political uncertainty, along with the need to adapt to high-risk lending, such as personal and business loans for low-income groups. The incomplete economic recovery after COVID-19 led to cautious borrowing behavior, slowing new loan disbursements and affecting overall credit growth in the industry.
Interest Rates and Government Regulations
Government interest rate control aims to protect consumers from excessively high interest charges. However, it may impact regulated credit providers, as interest rate caps could prevent them from setting rates that adequately cover costs, potentially reducing business profitability. Nevertheless, the Company adheres to an interest rate policy that is lower than the legal limit, considering customers' repayment capacity and current market conditions. This approach ensures that customers can access credit without excessive financial burden while maintaining business sustainability. As a result, the Company is not affected by interest rate regulations, as its set rates comply with legal requirements and strike a balance between profitability and customers’ financial capacity.
The increase in non-performing loans (NPL)
In a slowing economy with rising household debt, overall debt repayment capacity has declined, particularly among low-income groups, leading to an increase in non-performing loans (NPL). However, the Company has implemented strict lending practices, prioritizing customers' repayment ability, promoting financial discipline, and offering debt assistance measures to effectively manage risk. As a result, NPL in 2025 decreased from the previous year and remained at a satisfactory level. Additionally, the Company has enhanced portfolio management by leveraging AI technology for real-time data analysis, improving debt management efficiency and optimizing loan loss provisions.
Increased competition
The vehicle title loan business faces intensified competition as more providers enter the market. In 2025, competition focused on enhancing services and diversifying products to meet the needs of low-income customers, benefiting both consumers and the industry's overall growth. Despite this, the Company remained committed to service excellence, leveraging its 8,673 nationwide branches to ensure comprehensive community access. Additionally, the Company had expanded online platforms for greater convenience and customer reach while diversifying products to cater to various customer segments, resulting in the largest customer base and loan portfolio in the industry.
In 2025, the Company continued to expand efficiently and maintain satisfactory growth amidst high competition and market volatility. Effective risk management allowed the Company to operate sustainably. Furthermore, the Company prioritized all stakeholders to create positive impacts on society and the environment, while adapting to economic trends and market changes, positioning itself as a model for sustainable business development.
Procurement of Products & Services
Reporting Mode
3117
Procurement (Overall)
As of 31 December 2025, the Company’s major sources of funds consist of loans from financial institution amounting to 16.14 percent, borrowing through the issuance of bonds (debentures and bills of exchange) amounting to 55.55 percent with the finance sources from the shareholders amounting to 22.31 percent. Regarding the utilization of funds as of 31st December 2025, credits were granted to retail customers, among other uses.
Issued Bonds and Loans
As of 31 December 2025, and 2024, the outstanding bonds and domestic loans are as follows:
Unit: Million Baht | Interest rates (%) | Due | 2025 (million Baht) | 2024 (million Baht) |
Debentures | 2.02-5.82 | 2026-2033 | 105,890 | 88,567 |
Bills of exchange | 1.83-2.33 | 2026 | 490 | 2,961 |
Loans from financial institution | 2.93-4.97 | 2026-2031 | 31,043 | 32,796 |
Total | 137,423 | 124,323 | ||
Product Information — Overview
Introduction
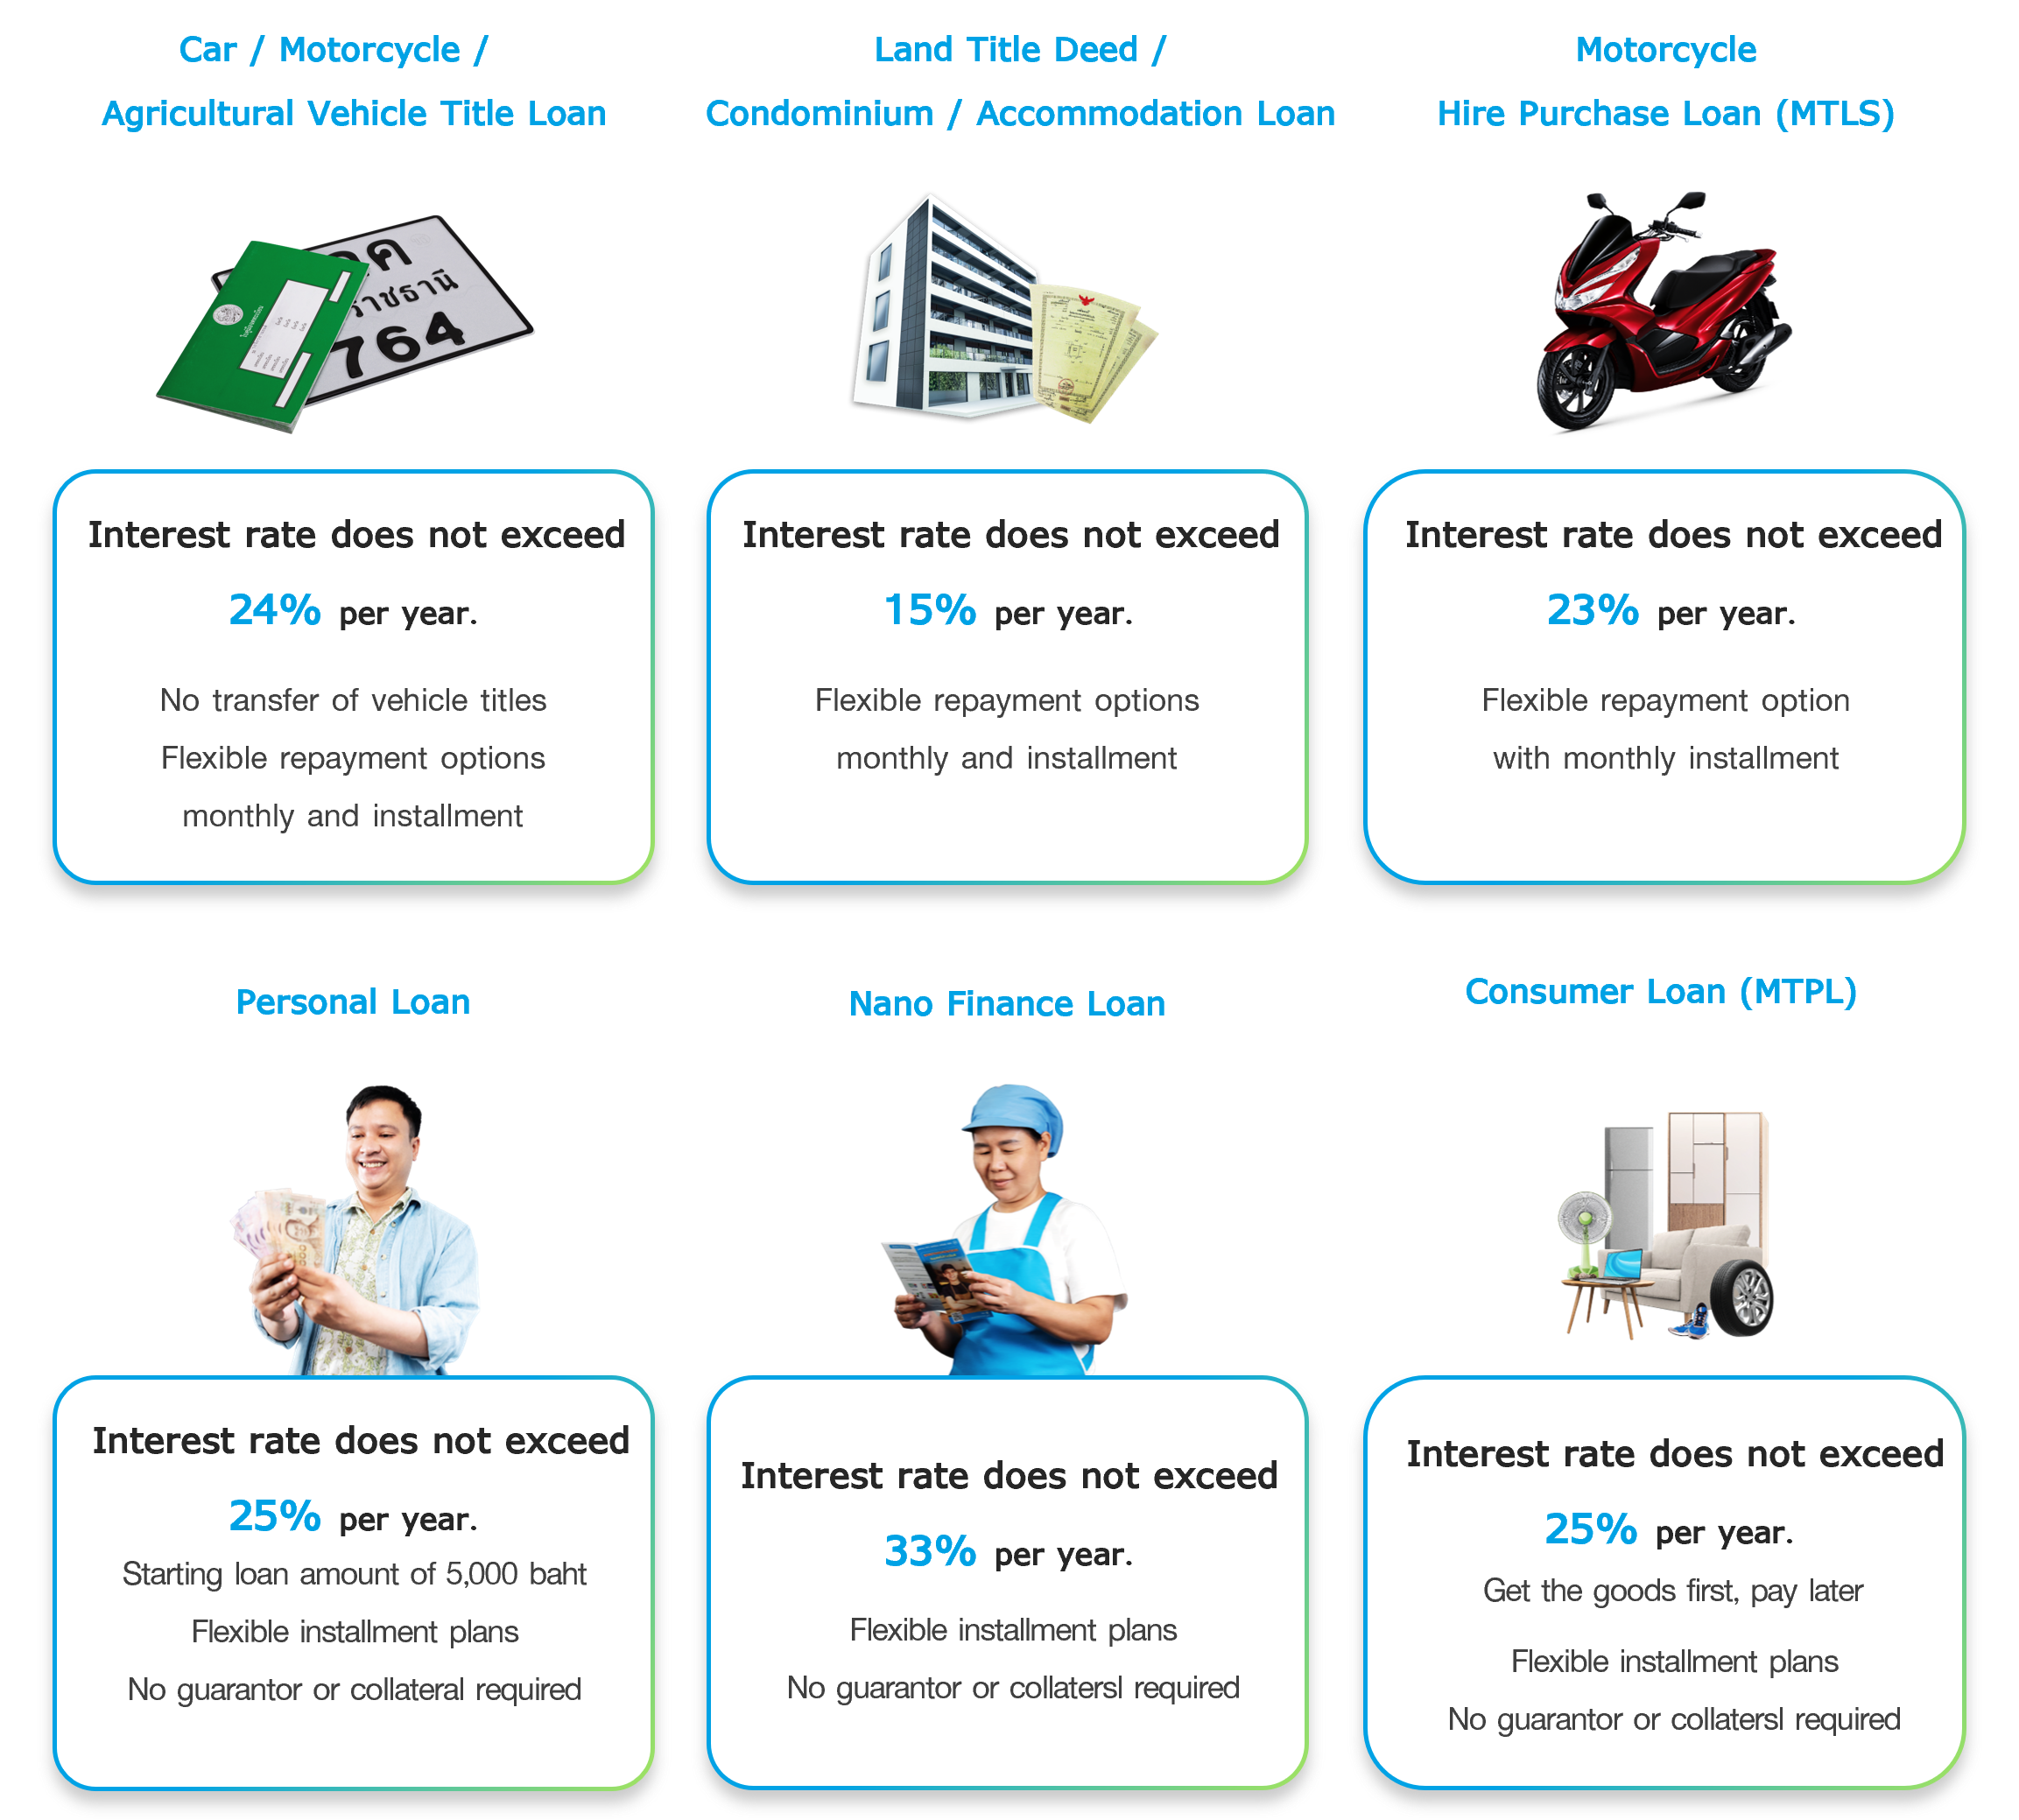
Since Muangthai Captial PCL. is a non-bank financial institution. The Company provide a financial service license under supervision from the Bank of Thailand. It allows to provide unsecured personal loans with the interest rate not exceeding 25% per annum, secured vehicle title loan with the interest rate not exceeding 24% per annum and to provide nano-finance loan for the occupation with the interest rate not exceeding 33% per annum. (The interest rates are according to Notifications of the Bank of Thailand, No. SorNorSor. 12/2563 on the regulations, methods and conditions for conducting personal loan business under supervision and No. SorNorSor. 13/2563 on the regulations, methods and conditions for conducting nano-finance service under supervision.)
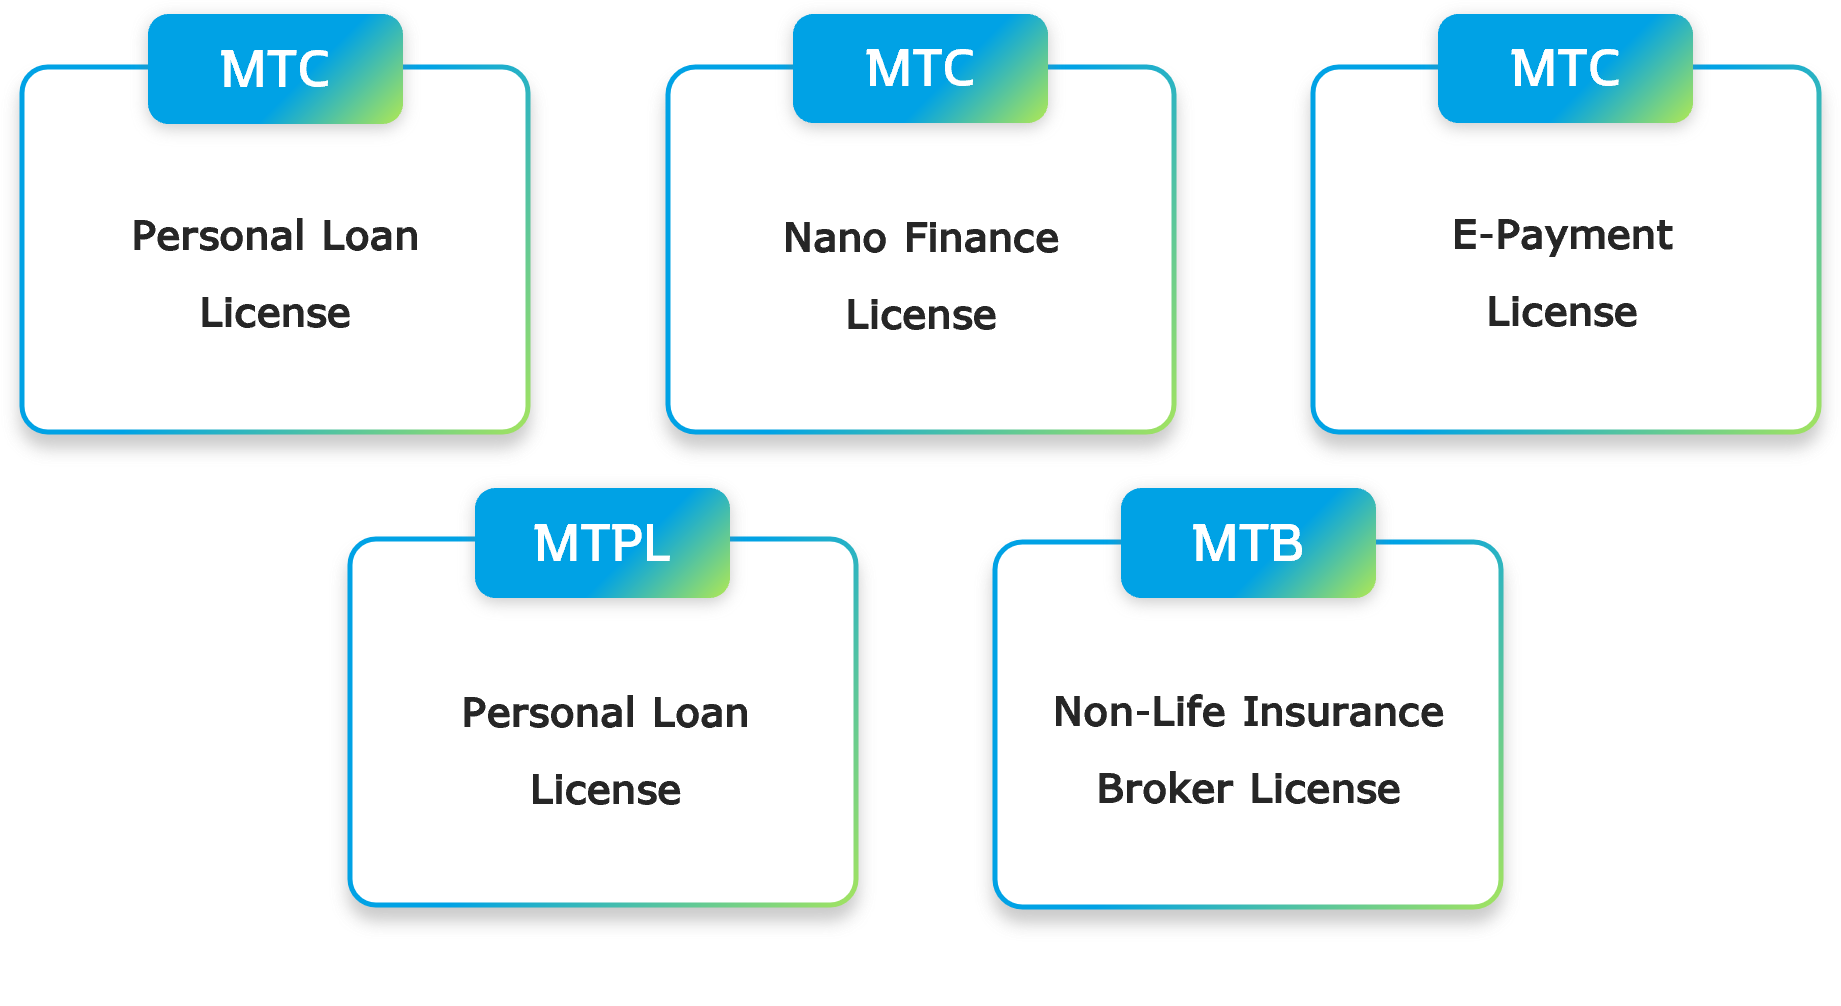
Furthermore, the Company has additional services operated by its subsidiaries; Muangthai Leasing Company Limited (MTLS) engages in motorcycle hire purchase loan business; Muangthai Pay Later Company Limited (MTPL) engages in consumer loan; Muangthai Leasing Insurance Broker Company Limited (MTB) engages in insurance brokerage business.
Licenses for the Loan Business Operations
Projects Under Construction
Has Projects Under Construction (Y/N)
No
Debentures & Bills of Exchange
Introduction
The Company’s major sources of funds are the shareholder’s equity and debts comprising loans from financial institutes. As of 31 December 2025, the Company had outstanding credits approved by the commercial banks amounting 31,043 million Baht and outstanding bonds totaling of 105,890 million Baht which were the issuance of debentures to financial institutes and major investors.
Information on the Company’s Debt Instruments Offered for Sale
In 2025, the Company issued and offered debentures both international and domestic debentures to investor 8 times for business operations to be used as working capital in the business and to repay the loans or debts from the issuance of debt securities or to finance or refinance in whole or in part, eligible social projects. The aggregate value of these senior and unsecured debentures is 107,005.54 million Baht.
Has Debentures (Y/N)
Yes
Debentures
| Debenture Name | Description / Rating | Interest Rate (%) | Outstanding | Maturity Date | Term | Types |
|---|---|---|---|---|---|---|
| Debenture of Muangthai Capital Public Company Limited No. 3/2564 Tranche 4 Due B.E. 2569 | Offering to institutional investors | 3.65 | 500 | 26 May 2026 | 5 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2564 Tranche 4 Due B.E. 2569 | Offering to general public | 3.7 | 996.4 | 25 Aug 2026 | 5 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 6/2564 Tranche 3 Due B.E. 2569 | Offering to general public | 3.7 | 1,000 | 3 Nov 2026 | 4.99 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2565 Tranche 2 Due B.E. 2569 | Offering to general public | 3.45 | 1,391 | 23 Feb 2026 | 4 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2565 Tranche 3 Due B.E. 2570 | Offering to general public | 3.7 | 1,000 | 22 Feb 2027 | 5 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2565 Tranche 2 Due B.E. 2569 | Offering to general public | 3.75 | 1,831.1 | 8 Jun 2026 | 4 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2565 Tranche 3 Due B.E. 2570 | Offering to general public | 3.9 | 933.2 | 7 Jun 2027 | 5 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 5/2565 Tranche 2 Due B.E. 2570 | Offering to institutional investors | 3.9 | 500 | 6 Jul 2027 | 5 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 8/2565 Tranche 2 Due B.E. 2569 | Offering to general public | 4 | 1,634.6 | 27 Apr 2026 | 3.5 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2566 Tranche 3 Due B.E. 2569 | Offering to general public | 4.1 | 1,995.2 | 16 Mar 2026 | 3.07 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2566 Tranche 4 Due B.E. 2570 | Offering to general public | 4.3 | 927.7 | 15 Mar 2027 | 4.06 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2566 Tranche 5 Due B.E. 2571 | Offering to general public | 4.5 | 1,121.1 | 13 Mar 2028 | 5.06 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2566 Tranche 3 Due B.E. 2569 | Offering to general public | 4.45 | 1,980.2 | 9 Jun 2026 | 3 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2566 Tranche 4 Due B.E. 2570 | Offering to general public | 4.65 | 1,519.2 | 8 Jun 2027 | 4 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 6/2566 Tranche 2 Due B.E. 2569 | Offering to general public | 4.7 | 1,399.7 | 25 AUG 2026 | 3.01 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 6/2566 Tranche 3 Due B.E. 2570 | Offering to general public | 4.8 | 1,332.4 | 24 Aug 2027 | 4 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 7/2566 Tranche 2 Due B.E. 2569 | Offering to general public | 4.75 | 1,064.4 | 3 Nov 2026 | 3.03 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 7/2566 Tranche 3 Due B.E. 2570 | Offering to general public | 4.9 | 812.7 | 2 Nov 2027 | 4.02 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 9/2566 Tranche 2 Due B.E. 2569 | Offering to general public | 4.4 | 592.2 | 9 Jun 2026 | 2.45 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 1/2567 Due B.E. 2569 | Offering to institutional investors | 4.3 | 170 | 23 Jan 2026 | 2 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2567 Tranche 1 Due B.E. 2569 | Offering to general public | 4.3 | 1,042.3 | 16 Mar 2026 | 2.02 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2567 Tranche 2 Due B.E. 2570 | Offering to general public | 4.8 | 1,999.7 | 15 Mar 2027 | 3.02 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2567 Tranche 3 Due B.E. 2571 | Offering to general public | 4.95 | 958 | 13 Mar 2028 | 4.02 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 3/2567 Tranche 1 Due B.E. 2570 | Offering to institutional investors | 4.8 | 250 | 15 Mar 2027 | 2.96 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 3/2567 Tranche 2 Due B.E. 2571 | Offering to institutional investors | 4.95 | 250 | 13 Mar 2028 | 3.96 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2567 Tranche 2 Due B.E. 2569 | Offering to institutional investors | 4.29 | 2,620 | 9 Apr 2027 | 2 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2567 Tranche 3 Due B.E. 2570 | Offering to institutional investors | 4.8 | 250 | 9 Apr 2027 | 3 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 5/2567 Tranche 1 Due B.E. 2569 | Offering to general public | 4.3 | 2,107.7 | 8 Jun 2026 | 2.06 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 5/2567 Tranche 2 Due B.E. 2570 | Offering to general public | 4.8 | 2,842.8 | 7 Jun 2027 | 3.06 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 5/2567 Tranche 3 Due B.E. 2571 | Offering to general public | 4.95 | 2,170.5 | 13 Jun 2028 | 4.08 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 6/2567 Tranche 2 Due B.E. 2569 | Offering to institutional investors | 4.29 | 710 | 9 Jul 2026 | 2 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 7/2567 Tranche 1 Due B.E. 2569 | Offering to general public | 4.3 | 768.8 | 25 Aug 2026 | 2.01 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 7/2567 Tranche 2 Due B.E. 2570 | Offering to general public | 4.8 | 1,061.2 | 24 Aug 2027 | 3.01 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 7/2567 Tranche 3 Due B.E. 2571 | Offering to general public | 4.95 | 754.4 | 29 Aug 2028 | 4.02 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 8/2567 Tranche 1 Due B.E. 2569 | Offering to general public | 3.5 | 852.8 | 3 Nov 2026 | 2.01 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 8/2567 Tranche 2 Due B.E. 2570 | Offering to general public | 3.8 | 1,468 | 2 Nov 2027 | 3.01 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 8/2567 Tranche 3 Due B.E. 2571 | Offering to general public | 4 | 1,679.2 | 7 Nov 2028 | 4.02 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 1/2568 Tranche 1 Due B.E. 2571 | Offering to general public | 3.9 | 2,371.2 | 13 Jun 2028 | 3.38 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 1/2568 Tranche 2 Due B.E. 2573 | Offering to general public | 4.2 | 1,165.9 | 26 Feb 2030 | 5.08 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 1/2568 Tranche 3 Due B.E. 2575 | Offering to general public | 4.6 | 1,462.9 | 24 Feb 2032 | 7.08 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2568 Tranche 1 Due B.E. 2569 | Offering to institutional investors | 0 | 5,000 | 11 Jun 2026 | 1.19 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2568 Tranche 2 Due B.E. 2570 | Offering to institutional investors | 0 | 4,700 | 1 Mar 2027 | 1.92 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 2/2568 Tranche 3 Due B.E. 2571 | Offering to institutional investors | 3.78 | 300 | 1 Aug 2028 | 3.34 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 3/2568 Tranche 1 Due B.E. 2572 | Offering to general public | 3.9 | 3,739.4 | 29 May 2029 | 4 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 3/2568 Tranche 2 Due B.E. 2573 | Offering to general public | 4.1 | 2,837.7 | 28 May 2030 | 5 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 3/2568 Tranche 3 Due B.E. 2575 | Offering to general public | 4.3 | 1,222.9 | 25 May 2032 | 6.99 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2568 Tranche 1 Due B.E. 2572 | Offering to general public | 3.8 | 3,182.9 | 4 Sep 2029 | 4.02 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2568 Tranche 2 Due B.E. 2573 | Offering to general public | 4 | 4,487.5 | 3 Sep 2030 | 5.02 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 4/2568 Tranche 3 Due B.E. 2575 | Offering to general public | 4.15 | 2,329.6 | 31 Aug 2032 | 7.01 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 5/2568 Due B.E. 2571 | Offering to institutional investors | 0 | 1,000 | 2 Oct 2028 | 3 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 6/2568 Tranche 1 Due B.E. 2571 | Offering to general public | 2.95 | 700 | 27 Nov 2028 | 3 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 6/2568 Tranche 2 Due B.E. 2572 | Offering to general public | 3.15 | 400 | 27 Nov 2029 | 4 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 6/2568 Tranche 3 Due B.E. 2574 | Offering to general public | 3.5 | 500 | 25 Nov 2031 | 6 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| Debenture of Muangthai Capital Public Company Limited No. 6/2568 Tranche 4 Due B.E. 2576 | Offering to general public | 4 | 900 | 27 Nov 2033 | 8.01 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| U.S.$50,000,000 Senior Unsecured Amortising Social Bond due August 2027 | Offering to institutional investors | 0 | 1,269.74 | 16 Aug 2027 | 2 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| U.S.$335,000,000 6.875 per cent. Senior Unsecured Amortising Social Notes due 2028 | Offering to institutional investors | 0 | 10,634.11 | 30 Sep 2028 | 4 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| U.S.$350,000,000 7.550 per cent. Senior Unsecured Amortising Social Notes due 2030 | Offering to institutional investors | 0 | 11,110.26 | 21 Jul 2030 | 5 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| U.S.$64,000,000 2.15 per cent. Senior Unsecured Guaranteed Social Notes due 2028 | Offering to institutional investors | 2.15 | 1,590.04 | 14 Oct 2028 | 3 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
| U.S.$65,000,000 2.28 per cent. Senior Unsecured Guaranteed Social Notes due 2030 | Offering to institutional investors | 2.28 | 1,614.89 | 14 Oct 2030 | 5 | 2789 · Description: Senior Debenture · 2791 · Description: Unsecured Debenture |
Convertible Securities
Has Convertible Securities (Y/N)
No